Buying
Buy in San Bruno and San Mateo County with sound information at every step.
Begin with a 30-minute planning call. We will cover your budget, the neighborhoods that fit it, what makes an offer competitive here, and how buyer representation works in California.
Step one
Know your numbers before you fall for a house.
Feeling "not ready" usually signals missing information. A lender pre-approval clarifies your monthly payment, your down payment and a realistic price range. From there, we match neighborhoods to your budget.
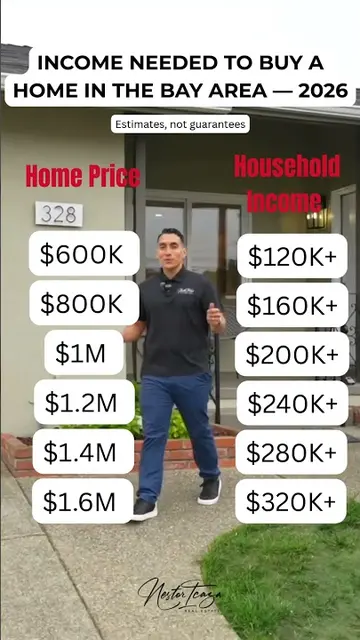
| Home price | Household income, roughly |
|---|---|
| $600,000 | $120,000+ |
| $800,000 | $160,000+ |
| $1,000,000 | $200,000+ |
| $1,200,000 | $240,000+ |
| $1,400,000 | $280,000+ |
| $1,600,000+ | $320,000+ |
Planning estimates from January 2026. Your down payment, debts, credit and interest rate will change the answer. Not lending advice; a licensed lender can confirm what you qualify for.
Inspections
What to examine in an older Peninsula home
Many San Bruno homes date from the 1940s to the 1960s. These are the items I ask buyers to examine closely:
- Roof and flashing. Patching, curling or soft spots, along with flashing around chimneys and skylights.
- Electrical panel. Zinsco and Federal Pacific panels appear in older homes and can affect both safety and insurance.
- Sewer lateral. Often excluded from a standard inspection. A sewer scope reveals roots and failing clay lines.
- Foundation and drainage. Grading toward the house and hillside runoff can lead to movement and moisture.
- Crawlspace. Standing water, a missing moisture barrier or a musty smell are warning signs.
- Attic. Leaks, pests and poor ventilation often surface here first.
- Permits. Confirm the age of major systems and whether additions and remodels were permitted.
- Windows and stucco. Stains around frames and cracks in stucco can indicate water intrusion.
Offers
The highest price does not always win.
In San Mateo County, sellers weigh certainty and simplicity alongside price. I help you structure offers that are strong on all three:
- Clean, uncomplicated terms
- Timing that works for the seller
- Proof of funds and a solid pre-approval at the outset
- Prompt, clear communication with the listing agent
- A loan and closing timeline the seller can rely on
Buying a 2 to 4 unit property?
Living in one unit and renting the others can help with both qualifying and carrying costs. I review rent rolls, leases, deposits and rent rules with you, and because I also run a property management company, I can show you what the building should cost to operate.
In their words: buyers I have represented
After two other agents
My wife and I had been looking to purchase our first home for years. We had engaged the services of two other agents yet neither had ever really clicked. [...] He provided meaningful advice, no-pressure recommendations, and kept our needs first and foremost. [...] When he seller violated one of the stipulations of our agreement during their move-out, Nestor negotiated the terms and got us a very fair outcome.
First-time buyer on a tight budget
I worked with Nestor for a couple of years before finding the one home for me. I was very particular about the type of property I wanted to buy, and a low budget and the scorching market did not help my cause. Nestor was very good at explaining the home buying process to me, a first-time home buyer. We'd spend hours reading disclosures, and eventually, I was able to read these on my own and know what to look for.
Buyer questions
Do I need to sign an agreement to work with a buyer agent?
Yes. Before we tour homes together, you will sign a written buyer representation agreement. It sets out my services, how I am paid and when the agreement ends. In California these agreements can run no longer than three months at a time, and you are welcome to ask me any question about it before signing.
Who pays the buyer agent?
Compensation is negotiable and is not set by law. In some transactions the seller offers to pay part or all of it; in others the buyer pays some or all. We agree on it in writing at the outset, and I will show you how it factors into each offer.
How much do I need for a down payment?
That depends on the loan. Some programs allow very small down payments; others require 20 percent or more. A lender pre-approval answers the question for your situation. I can introduce you to lenders, and you are free to choose your own.
Can I see homes that are not on the market?
Sometimes. I stay in contact with local owners and agents, and occasionally a seller will consider an offer before listing. Most purchases still originate on the MLS, so we monitor both.
Prefer to search on your own first? Browse homes for sale and set up listing alerts.